James Altucher has spent nearly four decades in technology and investing. He is a Wall Street Journal best-selling author, a venture capitalist, and someone who has worked on artificial intelligence research since the late 1980s. In a recent presentation he walks through what he calls Elon Musk’s “Infinite Money Glitch” and argues that a major shift is already underway. The core claim is straightforward: Elon is building a self-improving physical robot system that could generate enormous new wealth, and the biggest gains may not come from owning Tesla itself but from a small group of supplier companies that sit at the bottlenecks of that system.
What the Infinite Money Glitch Actually Is
Altucher opens with drone footage of a large construction site that, only weeks earlier, had been undeveloped land. The site is described as a new factory belonging to one of Elon’s companies. Inside that factory, according to the presentation, Elon is preparing to produce what he has privately called an “Infinite Money Glitch.” Publicly the product is known as Optimus, a humanoid robot powered by the same kind of artificial intelligence that already writes large portions of the code at the leading AI labs.
The key idea is simple. Today’s most advanced AI systems still live inside computers and data centers. They can design chips, write code, and improve their own architectures, but they cannot reach out and perform physical work. Optimus is meant to close that gap. The robot is designed to walk, use tools, perform household tasks, and eventually work inside factories—including factories that build more Optimus robots. Because every unit is connected to a shared neural network, a skill learned by one robot can be sent wirelessly to every other robot. The system therefore improves continuously and can, in theory, scale without the normal limits of human labor.
Altucher quotes Elon describing the project as “the biggest product ever made.” He also notes that Elon’s own compensation package, set by Tesla’s board in 2025, includes specific milestones tied to Optimus deliveries. One of those milestones requires at least one million robots. That incentive structure is presented as further evidence that the company is serious about moving from prototypes to volume production.
The presentation repeatedly returns to a single date: October 21, 2026. Altucher expects a public announcement around that time that will make the scale of the project clearer to the broader market. Until then, he argues, the opportunity remains relatively quiet.
The Scale of the Claimed Opportunity
Numbers this large need careful handling. Altucher cites a statement from Elon that the Infinite Money Glitch could grow the global economy by a factor of ten or possibly one hundred. A tenfold increase, applied to current global output, produces a figure of roughly $1.26 quadrillion in additional annual economic activity within a decade. The presentation then compares that number to the U.S. national debt and to per-person checks of several million dollars. The point is not that every person will receive such a check; the point is that the total new output would be large enough to create concentrated wealth for those positioned early in the supply chain.
To support the idea that these magnitudes are not pure fantasy, Altucher turns to research from the Federal Reserve Bank of Dallas. In a paper on the economic effects of artificial intelligence, the Dallas Fed discusses the technological singularity—the point at which machines improve themselves faster than humans can keep up. Their illustrative projections show U.S. economic output reaching roughly $90 trillion by 2030, $390 trillion by 2035, and approaching $2 quadrillion by 2040 under a strong singularity scenario. Adjusted into today’s dollars, those figures imply annual output per person in the multi-million-dollar range. Altucher notes that even if the actual numbers land lower, the direction of travel is still extraordinary.
He is careful to add the standard caveat that past performance is no guarantee of future results and that no one can put a precise price tag on an event the world has never seen. The presentation’s purpose is to show that the upper end of the possible range is large enough to justify serious attention.
Why Suppliers Matter More Than the Headline Company
A central theme of the research is that the biggest returns in past technology waves rarely went to the most famous company. They went to the firms that supplied critical, hard-to-replace components when demand suddenly exploded.
Altucher offers several historical examples drawn from Tesla’s own growth. In the years surrounding Tesla’s push toward one million vehicle deliveries, Tesla shares roughly doubled over a multi-year stretch. Modine Manufacturing, which supplied thermal-management systems, rose more than 4,500 percent over a comparable period. When Tesla secured battery supply, CATL shares climbed more than 400 percent in under two years. Albemarle, a lithium supplier, multiplied roughly six times from early 2020 into late 2022. Similar patterns appear in the recent AI boom: Nvidia delivered the largest gains for investors who owned the chips, while memory suppliers such as Micron also produced outsized returns once demand accelerated.
The argument is that every new product category creates bottlenecks. Existing supply chains are rarely ready for sudden volume. The companies that already dominate those narrow points of the chain can see rapid order growth and corresponding stock-price moves. Altucher states that he has spent months identifying three such companies for the coming wave of physical AI and humanoid robots. He describes them in functional terms:
- The vision supplier: a company whose sensors already serve as the “eyes” for a large majority of advanced driver-assistance systems. Its leadership has publicly committed capital to the physical-AI market and has named AI robots as a direct target.
- The nervous-system supplier: the leading maker of specialized magnetic chips that give robots precise knowledge of the position of every joint. Management estimates that an advanced AI robot will use roughly 150 of these chips—about double the number found in some electric vehicles.
- The motor-control supplier: a firm that provides the microcontrollers, sensors, and motor-control components that allow robots to grip firmly yet handle delicate tasks. It has been named a partner in Nvidia’s robotics platform and has been highlighted by Morgan Stanley as part of the emerging humanoid supply chain.
These three firms, according to the research, stand to receive orders regardless of which robot maker ultimately leads the market. Tesla’s Optimus, Amazon’s warehouse robots, Boston Dynamics’ Atlas, Figure AI’s machines, Unitree’s lower-cost models, and others all require the same basic capabilities: sight, proprioception, and precise motor control. The presentation insists that the names, ticker symbols, and suggested entry prices appear only inside the featured research report that comes with membership.
How AI Is Already Improving Itself
Before focusing on robots, Altucher spends time establishing that the intelligence explosion is already visible inside software. Google’s AlphaChip designs the microchips used to train its Gemini models. AlphaEvolve writes code that improves neural-network architecture and data-center efficiency. At Anthropic, more than 90 percent of the company’s code is now written by its own AI system, Claude. OpenAI reports that AI writes roughly 80 percent of its code; Google reports a similar figure of 75 percent.
Independent researchers at METR have tracked the length of tasks that AI systems can complete reliably. In 2019 the doubling time for that capability was about seven months. By 2026 the doubling time had shortened to roughly four months. The trend line points toward systems that can handle work that would take human teams decades or centuries.
These observations are presented as confirmation of a forecast made more than sixty years ago by computer scientist I.J. Good. Good described an “intelligence explosion” in which machines design better machines until progress becomes self-sustaining. Elon Musk’s recent five-word post—“We have entered the Singularity”—is treated as a public acknowledgment that the process is no longer theoretical.
Physical AI is framed as the final missing piece. Once the same self-improving intelligence can operate outside the screen, the feedback loop expands into the real economy. Robots that build robots, that learn from one another, and that never take breaks become the practical expression of that loop.
The Broader Competitive Landscape
Elon is not working in isolation. The presentation surveys other large efforts already under way:
- Nvidia is building virtual training environments and dedicated robot brain chips.
- Amazon operates more than one million robots in its warehouses and is testing more advanced AI models that walk the floor.
- Boston Dynamics plans to produce 30,000 of its all-electric Atlas robots per year by 2028.
- Unitree sells walking robots for roughly the price of a used car.
- Figure AI, backed by Nvidia, Microsoft, and Jeff Bezos, is already valued at $39 billion and has robots working on BMW lines.
- 1X is building capacity for one hundred thousand home robots a year by 2027 and sold out its first year of production in five days.
- Apptronik, backed by Google and Mercedes, is valued at $5.5 billion.
- Apple is reported to be exploring its own home robot.
Jensen Huang of Nvidia has summarized the direction as “robots building robots building robots.” The common thread is that every one of these systems will need the same foundational components that the three supplier companies provide. Diversification across suppliers rather than a single robot maker is therefore presented as the more robust approach.
Altucher’s Track Record and Perspective
Altucher spends time establishing his own history so readers can judge the source. He began AI work at Cornell in the late 1980s and continued in graduate school at Carnegie Mellon, where he shared an office with the team building the chess computer that later became Deep Blue. He presented a paper on machine reasoning at a major conference in 1990. He later ran a hedge fund that used AI methods when few on Wall Street did, and he continues to advise public technology companies involved in the current AI build-out.
He cites three public predictions that were widely dismissed at the time: that Facebook would one day be worth more than $100 billion (made on CNBC while the company was still private), that Apple would become the first trillion-dollar company, and that streaming video over the internet would become mainstream long before Netflix proved the model. Each of those calls looked extreme when first made and later proved accurate. The presentation does not claim perfection; it claims a consistent habit of taking large technological shifts seriously before they become obvious.
The Research Offer and What Members Receive
The presentation is not purely informational. It is an invitation to join Altucher’s Investment Network. The structure of the offer is laid out in clear terms.
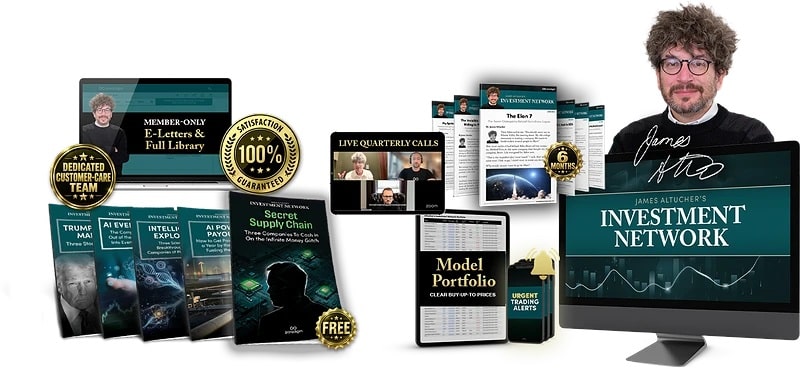
For a single payment of $49 (reduced from a regular six-month price of $299), a new member receives:
- Six months of Altucher’s Investment Network, including monthly research on the Infinite Money Glitch and other major technology trends.
- The featured report “Secret Supply Chain: THREE Companies To Cash in On the Infinite Money Glitch.” This report names the three supplier companies, explains why each is difficult to replace, and provides the prices Altucher would currently pay.
- Four additional bonus reports that together form the Infinite Money Glitch Masterkit:
- Trump’s Robot Mandate: 3 Stocks Set to Surge — three companies expected to benefit from potential U.S. policy support for domestic robotics, including fast-tracked permits and federal contracts.
- AI Everywhere: The Company Bringing AI out of the Data Center and into Everything You Touch — a firm that has spent two decades placing efficient AI chips inside consumer and industrial devices and has recently released a dedicated chip for humanoid robots.
- Intelligence Explosion: Three Science Fiction Breakthroughs, and the Companies at the Center of Each — one company focused on automated AI laboratories for drug discovery, one supplier of critical hardware for fusion energy, and one established firm with a long dividend-growth record that is active in quantum computing.
- AI Power Payouts: How to Get Paid Four Times a Year by the Company Fueling the AI Boom — a company that owns energy infrastructure serving AI data centers and is structured to distribute the bulk of its cash flow to owners through regular quarterly payments.
Additional membership benefits include:
- Access to the current model portfolio with explicit buy-up-to prices on every open position.
- Weekly updates and urgent alerts when it is time to buy, add, or take profits.
- Full access to the member library of past issues and special reports.
- Quarterly live interactive Zoom calls.
- A U.S.-based customer-care team available 9 a.m. to 6 p.m. Eastern Time.
The total stated value of the reports and six months of service is $624. The introductory price is $49. Membership is covered by a 90-day, 100 percent money-back guarantee. If a member cancels for any reason within that window, a full refund is issued and the five reports may be kept.
Altucher emphasizes that the service is written for ordinary investors, not professional traders. Recommendations come with plain-English explanations and clear price levels. No personalized investment advice is offered; each reader decides position size and timing independently.
Risks and Realistic Expectations
Every investment carries risk. The presentation does not claim otherwise. Robot production schedules can slip. Competing designs can gain share. Component demand can rise more slowly than expected. Regulatory or trade-policy changes can alter the competitive landscape. Stock prices can fall even when the underlying technology succeeds.
The research approach tries to manage those risks by focusing on suppliers rather than a single end-product company and by spreading exposure across several related themes: vision sensors, joint-position chips, motor controllers, policy beneficiaries, edge-AI chips, drug-discovery platforms, fusion infrastructure, quantum-related hardware, and energy infrastructure that pays regular dividends. Position sizes remain the reader’s choice. The 90-day guarantee removes the membership cost as a barrier to evaluating the material.
Readers are reminded that even a successful technology wave produces uneven results across individual stocks. Past supplier gains of several hundred or several thousand percent are historical observations, not forecasts of future performance.
Timeline and Urgency
The October 21, 2026 date is presented as a potential catalyst. Once a major public demonstration or production update occurs, broader awareness is expected to rise and the relatively quiet pricing of the supplier stocks may change. Altucher argues that the window of lowest attention is therefore the present moment. He does not claim the date is certain—only that it is the point at which he expects visibility to increase sharply.
Putting the Pieces Together
The overall thesis can be summarized in a few sentences. Artificial intelligence is already writing most of the code that improves the next generation of artificial intelligence. The remaining barrier is physical embodiment. Humanoid robots such as Optimus are designed to provide that embodiment and, over time, to manufacture more of themselves. When production scales, demand for a small set of specialized components—vision sensors, joint-position chips, and motor-control electronics—will rise across multiple robot makers. History shows that the firms occupying those bottlenecks have often delivered the largest percentage gains.
Altucher’s research identifies three such firms and adds four complementary reports covering related policy, edge computing, scientific breakthrough, and income themes. Access to the full set of names, tickers, and suggested entry prices is available through a six-month membership offered at a reduced introductory price with a full money-back period.
Whether any individual reader decides the opportunity is worth acting on is a personal decision that depends on risk tolerance, time horizon, and existing portfolio. The presentation’s purpose is to place the information in front of people who would otherwise encounter it only after the largest early moves have already occurred.